California’s 2027 SaaS Tax Mandate: Why Software Companies Must Upgrade Their Billing Stack Now
5 mins
September 21, 2026
The Regulatory Shift in California
Historically, software companies enjoyed a straightforward tax environment when selling into California. As long as software arrived over an internet connection rather than on physical media, California state tax rules considered it an intangible service exempt from sales tax. B2B software companies could generally scale to tens of millions in recurring revenue without charging tax or managing complex state sales tax filings.
That tax-free era for cloud software is rapidly closing. Governor Gavin Newsom signed California Senate Bill 122 into law, expanding the definition of taxable personal property to include remotely accessed prewritten software and Software-as-a-Service. Beginning January 1, 2027, software sales into California will incur the state base rate of 7.25% plus local district surcharges. According to a PwC tax alert, SB 122 fundamentally alters the economic and administrative cost structure for software vendors and buyers.
As the fifth-largest economy in the world and the single largest market for enterprise software, California's policy shift radiates across the entire global B2B technology landscape.
What Transactions are Taxable
Many software executives operating outside California may assume state tax law changes only affect local companies headquartered in Silicon Valley or Los Angeles. That assumption creates severe compliance exposure. Under SB 122, taxability for software transactions relies strictly on the location of the buyer rather than the location of the seller, as detailed in a Sales Tax Institute report.
The sale location is determined based on the buyer’s known address, following a hierarchy to determine the address:
- Primary billing address on record
- Shipping or delivery address
- Address associated with the payment instrument
- Any other known mailing address in customer records
If a buyer's record points to California, the transaction triggers California sales tax obligations regardless of whether the software provider is based in Austin, London, or Sydney. Global sellers meeting general economic nexus thresholds must register with the California Department of Tax and Fee Administration, calculate district-specific tax rates, collect tax on invoices, and remit payments. Custom software created for a single customer remains exempt, but standard configurable SaaS platforms fall directly within scope.
Failing to account for these new tax rules creates compounding financial liabilities that surface at the worst possible moments.
The Financial and Audit Exposure of Non-Compliance
Ignoring state tax obligations rarely results in a minor administrative fine. California enforces significant penalties for unpaid sales tax under the California Revenue and Taxation Code. Standard late filings trigger an immediate 10% penalty, while failure to exercise ordinary care adds an additional 10% negligence penalty.
When a vendor collects tax from customers but fails to remit those funds to the state, penalties can reach 40%. Compounding daily interest accumulates on top of these base penalties. In practice, a standard audit by state tax authorities can increase total back-taxes and fees by 30% to 50% above the original liability.
Beyond direct state penalties, unmanaged tax exposure routinely delays or disrupts venture capital investment rounds, M&A due diligence, and IPO readiness. Institutional buyers regularly demand dollar-for-dollar escrows or valuation discounts to cover unrecorded tax liabilities.
Avoiding these costly audit penalties requires software companies to upgrade their billing and financial workflows well before enforcement begins.
Why Upgrade Now
Waiting until late 2026 to prepare for SB 122 invites severe billing errors and customer friction. Implementing tax compliance across a subscription model requires engineering, accounting, and RevOps preparation.
Software leadership teams should focus on five operational priorities:
- Auditing customer location records: Verify completeness of billing address data across active customer accounts to establish proper taxation jurisdictions.
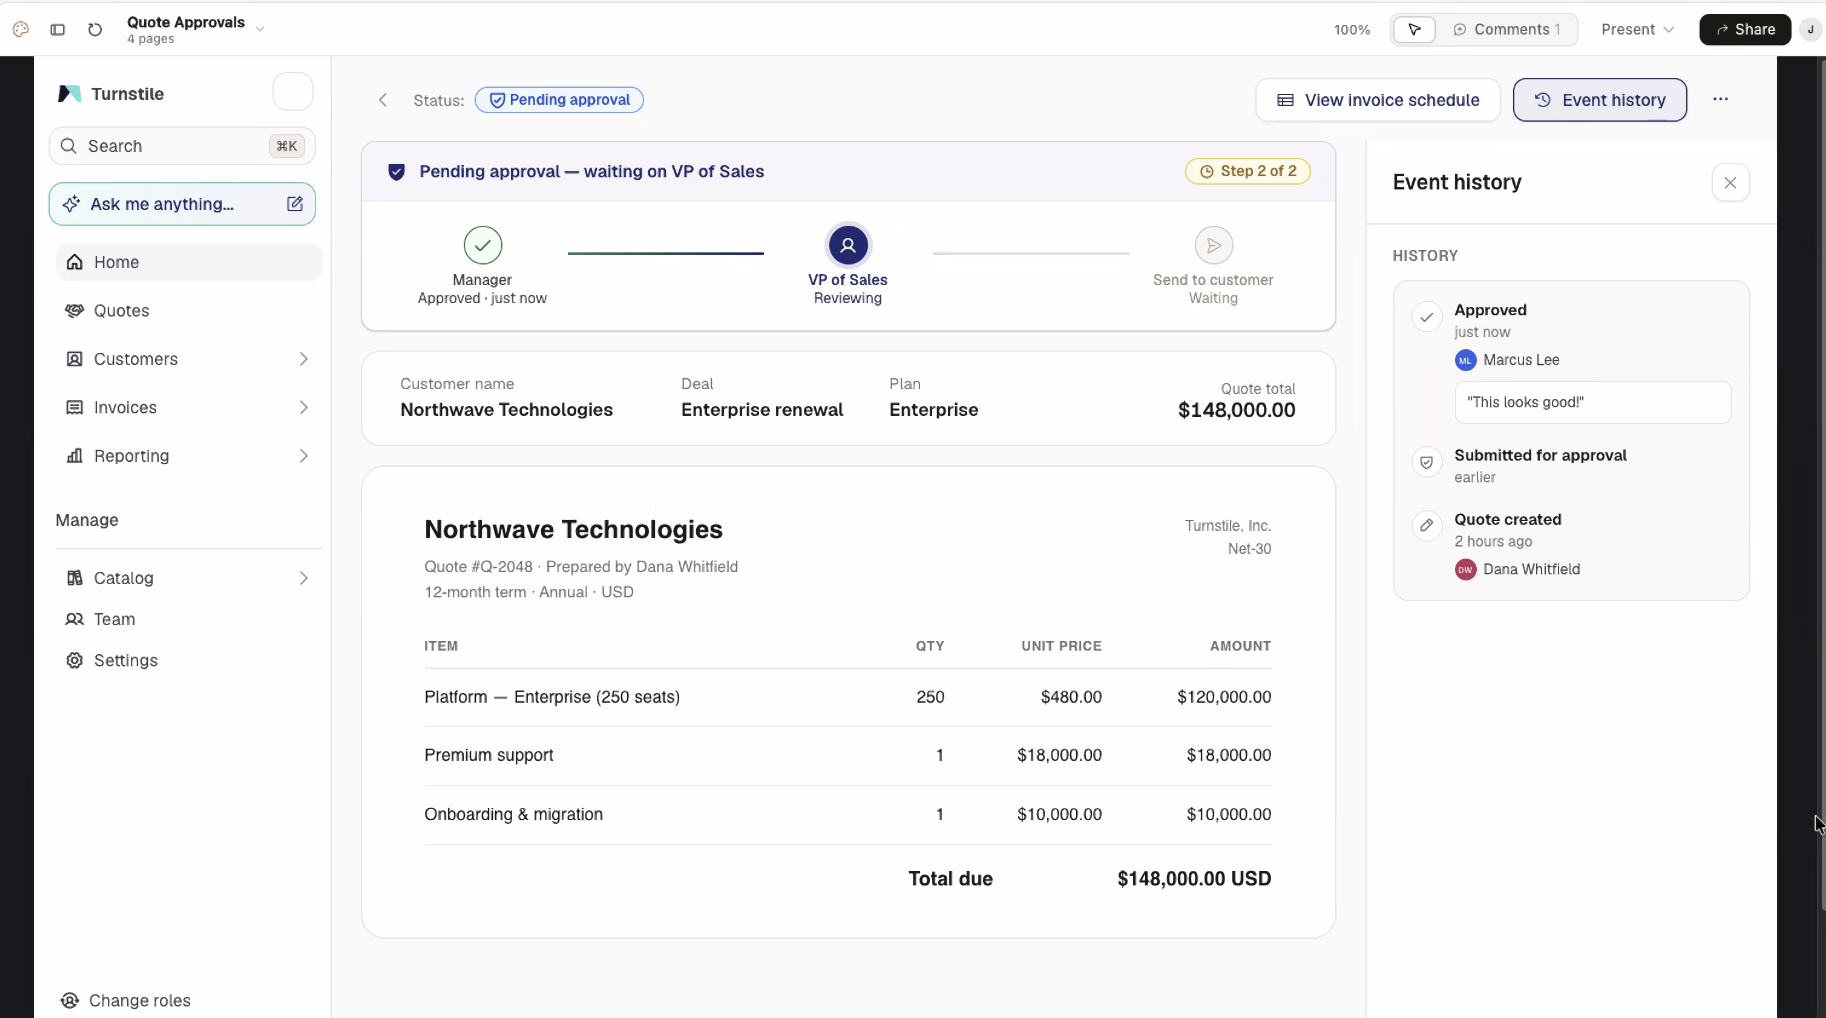
- Stop manual invoicing: You need a billing and invoicing system that stores invoice lines and addresses as structured data.
- Integrating tax calculation engines: Connect automated tax calculation software directly into billing and invoicing systems.
- Contract unbundling: SB 122 taxes prewritten software but exempts pure human services like strategy consulting, implementation, and managed services. Revenue teams must unbundle mixed contracts into clear line items on invoices so non-taxable services are not inadvertently taxed.
- Updating customer agreements: Adjust master service agreements and order forms to clarify that applicable sales taxes are the responsibility of the customer and will be added to invoices.
Completing these updates ensures compliance for California while positioning businesses to navigate broader changes in software monetization.
Revenue Infrastructure Beyond Tax Compliance
California’s decision to tax digital software reflects a broader shift across domestic and international jurisdictions. Taxing authorities around the world continue to broaden tax definitions to capture digital products and cloud services (for example, the EU Digital Services Act). Attempting to manage these requirements with manual spreadsheets or rigid legacy billing tools creates unnecessary risk and errors.
Modernizing your billing stack accomplishes far more than satisfying tax authorities. Connecting subscription workflows to dynamic tax engines establishes the technical foundation needed to support usage-based pricing, hybrid contract models, international currencies, and enterprise deal structures. In a market where software monetization is becoming more complex, treating revenue architecture as vital core infrastructure is a requirement to scale effectively.